Table of Contents
- What Counts as a Surprise Medical Bill?
- Your Rights Under the No Surprises Act
- Step-by-Step: How to Dispute a Medical Bill
- TRICARE Breast Pump Coverage and Maternity Support
- How Insurance Authorization for Maternity Supplies Works
- Protecting Your Credit From Medical Debt
- Conclusion
- Frequently Asked Questions
Last Updated: September 28, 2026
What Counts as a Surprise Medical Bill?
A surprise medical bill is a charge for care you reasonably believed your health insurance plan would cover, but which arrives from an out-of-network provider you never chose. The most common sources are emergency room visits, ambulance rides, and care from a specialist at an in-network facility who turns out not to be in your network.
A surprise bill is not the same as a normal deductible or copayment. It is a bill for out-of-network care you did not knowingly choose.
Your Rights Under the No Surprises Act
The No Surprises Act is a federal law that protects patients from most surprise medical bills for emergency care and for certain non-emergency care at in-network facilities. It took effect in 2022 and applies to most group health plans and individual health plans.
Emergency Services Protections
Emergency services protections cover you whether or not the hospital or doctor is in your provider network. If you have an emergency and receive care, you are entitled to in-network cost-sharing rates.
Non-Emergency Services at In-Network Facilities
Non-emergency services at in-network facilities are protected too, but with a catch. If you go to an in-network hospital or clinic and an out-of-network provider treats you, you are generally protected from balance billing.
| Situation | Are You Protected? | What To Do |
|---|---|---|
| Emergency care, out-of-network | Yes, in most cases | Pay only in-network cost-sharing |
| Non-emergency at in-network facility | Yes, unless you signed consent | Check for a signed consent form |
| Non-emergency at out-of-network facility | Usually no | Ask for a cost estimate first |
| Ambulance or air transport | Often yes | Review your plan’s specific rules |
Step-by-Step: How to Dispute a Medical Bill
Disputing a medical bill is a paperwork process, not a confrontation. Work through these steps in order and keep a written record of every call, letter, and portal message.
- Request an itemized bill. Ask the billing department for a line-by-line statement (sometimes called a “UB-04” for hospital charges or a “CMS-1500” for physician charges), not a summary. Summaries hide duplicate line items and upcoded visits.
- Compare it to your explanation of benefits (EOB). The EOB is your insurer’s official record of what was billed, what was allowed, and what you owe. Any gap between the EOB and the bill is your first dispute hook.
- Check for billing errors. Duplicate charges, wrong billing codes, services you never received, and wrong dates of service are the most common errors. Flag each one in writing.
- Call your insurance company. Ask whether the claim can be reprocessed at in-network rates under the No Surprises Act. Get the representative’s name and a reference number for the call.
- Ask for the internal appeal process. Every plan has one. Ask for the deadline to file and the address or portal where appeals go.
- Send a written dispute letter. Include your member ID, claim number, date of service, and a clear explanation of what you want fixed. Send it certified mail with return receipt.
- Escalate to your state department of insurance. If the plan will not budge after the internal appeal, your state department of insurance can open a complaint. Many states accept complaints online.
- If the bill is from an out-of-network provider, ask about federal Independent Dispute Resolution (IDR). Under the No Surprises Act, certain out-of-network bills go to a federal arbitration process between the provider and the insurer, not to you. You generally should not be billed while that process plays out.
Dispute Letter Template
To: [Insurance Company Name], Claims Review Department
Re: Claim #[number], Member ID #[number], Date of Service: [date], Provider: [name]
I am disputing a charge of [amount] from [provider name]. This care was [emergency care / received at an in-network facility]. I did not consent in writing to out-of-network care, and I am requesting that this claim be reprocessed at my in-network cost-sharing rate and that any balance billing be removed.
I am also requesting a written explanation of benefits showing the reprocessed claim. Please respond in writing within 30 days.
Sincerely,
[Your name, address, phone, email]
Escalation Letter Template
If the internal appeal fails, escalate in writing:
To: [State] Department of Insurance, Consumer Complaints Division
I am filing a complaint against [insurer name] regarding claim #[number]. I have attached my EOB, the provider bill, and my written appeal to the insurer dated [date]. I believe this bill violates the No Surprises Act because [reason]. I am requesting that the department review the claim and direct the insurer to reprocess it at in-network rates.
Send dispute letters by certified mail and keep the receipt. A dated paper trail moves claims faster than phone calls alone, and it gives your state department of insurance something concrete to act on. Keep a simple log with the date, the person you spoke with, and what they promised.
Protecting Your Credit While You Dispute
You can dispute a bill and protect your credit at the same time. Under federal law, you have the right to request validation of a debt from a collector, if they cannot prove you owe it, they must stop collecting. If a medical collection appears on your credit report while a dispute is open, you can file a dispute with each credit bureau (Equifax, Experian, and TransUnion) and ask them to mark the account as disputed.
TRICARE Breast Pump Coverage and Maternity Support
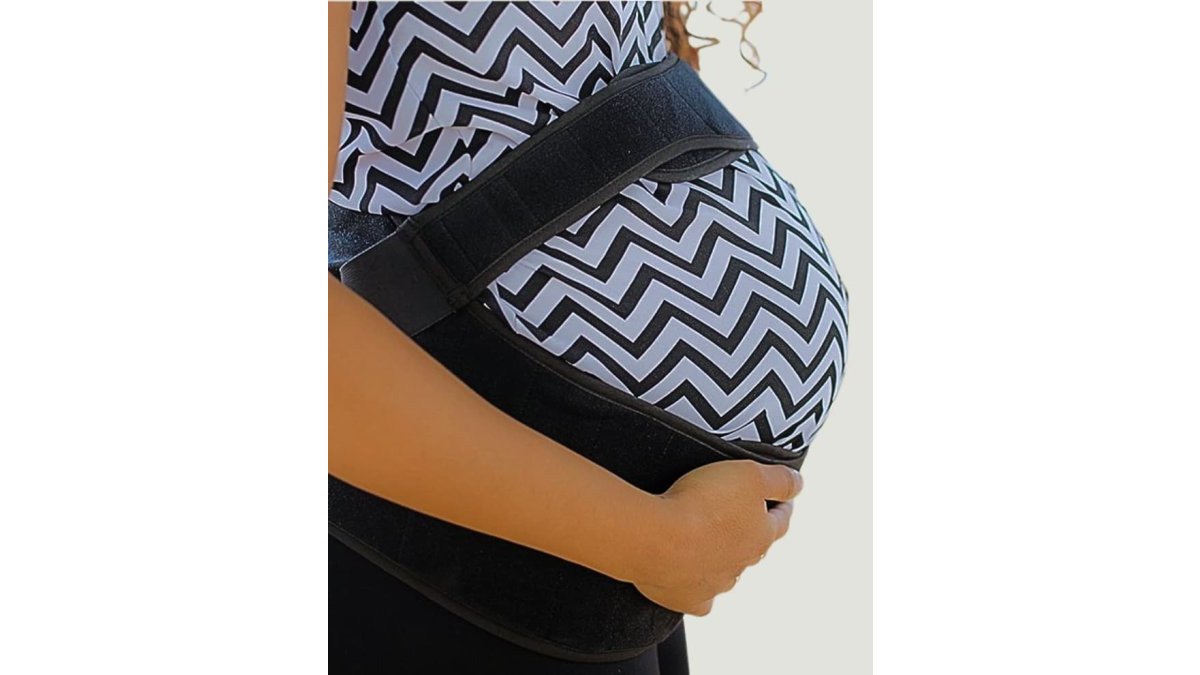
TRICARE breast pump coverage gives eligible expectant and new mothers access to a breast pump and related supplies as a covered maternity benefit. Maternity back support and postpartum abdominal binders may also be covered when a provider prescribes them.
Check Your Insurance Coverage →
What TRICARE Covers
TRICARE generally covers:
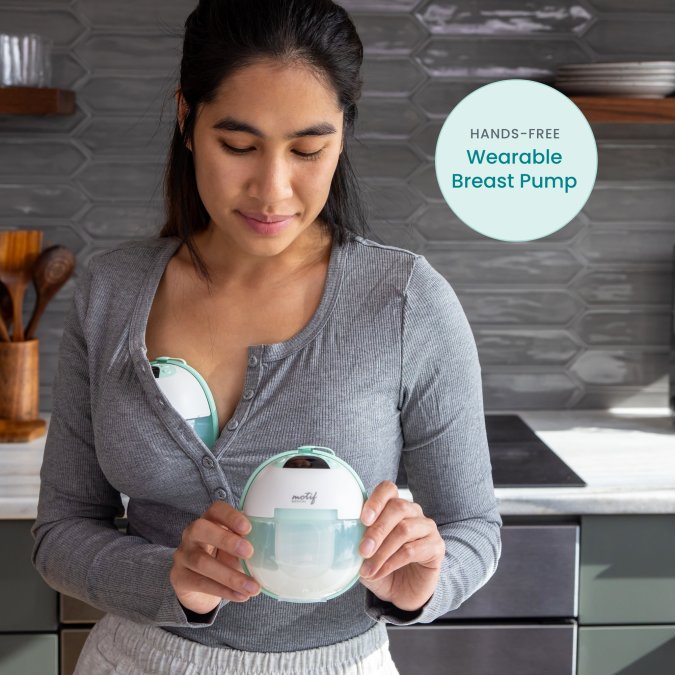
- A manual or electric breast pump (including hands-free models) for mothers who are breastfeeding
- Breast pump supplies and replacement parts
- Maternity back support and postpartum abdominal binders when medically necessary and prescribed
The benefit typically applies during pregnancy and for a set window after delivery. Because plan rules vary by TRICARE plan (Prime, Select, or TRICARE For Life) and by whether you use a military hospital or a civilian provider, confirm your specific benefit details with your plan before you order.
How the Authorization Process Works
Insurance authorization for maternity supplies follows a set path, and knowing it helps you spot delays early.
A typical order moves through four stages:
- Your provider writes a prescription for the equipment.
- The supplier submits it to your plan for verification.
- Your insurer confirms your benefits and issues authorization.
- The supplier ships the item to your home.
How We Handle It for You
This is where General Home Medical Supply does the heavy lifting. We handle prescription coordination and get all the authorization from your insurance company, then ship the breast pump and maternity back support to your home at no charge, with free shipping.
Do not order a pump before your prescription is on file. A pump bought without authorization may not be reimbursed, and you could be stuck paying out of pocket for equipment you were entitled to receive.
If you have TRICARE and need a hands-free breast pump or maternity back support, we secure the authorization from your insurance and ship the equipment to your home at no charge, with free shipping.
How Insurance Authorization for Maternity Supplies Works
Insurance authorization for maternity supplies follows a set path, and knowing it helps you spot delays early.
A typical order moves through four stages:
- Your provider writes a prescription for the equipment.
- The supplier submits it to your plan for verification.
- Your insurer confirms your benefits and issues authorization.
- The supplier ships the item to your home.
Protecting Your Credit From Medical Debt
Medical debt can reach your credit report, and the rules around it have tightened in recent years. The Consumer Financial Protection Bureau’s guidance on medical debt outlines how medical collections are treated and what collectors can and cannot do.
Three habits protect your credit:
- Open every explanation of benefits and compare it to the bill.
- Dispute questionable charges in writing within the first billing cycle.
- Never pay a bill you believe is wrong just to make it go away.
Conclusion
Surprise medical bills are stressful, but the law is on your side more often than most people realize. Check every bill against your explanation of benefits, dispute errors in writing, and lean on the No Surprises Act when an out-of-network charge shows up.
Frequently Asked Questions
What is considered a surprise medical bill under the No Surprises Act?
A surprise medical bill happens when you receive care from an out-of-network provider without your knowledge, often during emergencies or at in-network facilities where you had no choice in the provider. The No Surprises Act protects you from balance billing in these situations. If you receive a bill for emergency services or from an out-of-network provider at an in-network facility, that bill may violate federal law. You generally cannot be charged more than your in-network cost-sharing amount for these services.
Are maternity supplies like breast pumps covered by TRICARE?
TRICARE covers breast pumps and maternity support supplies for eligible beneficiaries. Coverage typically requires a prescription from your healthcare provider and authorization from TRICARE before the item ships. General Home Medical Supply handles the entire authorization process for you, coordinates with your provider, and ships your breast pump and maternity back support directly to your home. Shipping is free, and there is often no cost to you. Check your specific TRICARE plan for coverage details.
What steps should I take if I receive an unexpected medical bill?
First, do not pay the bill immediately. Request an itemized statement and compare it to your explanation of benefits from your insurance company. Check whether the provider was in-network and whether the service falls under No Surprises Act protections. If you believe the bill is incorrect, contact your insurance company and the provider’s billing department. You can also file a dispute with the appropriate federal or state agency. Keep records of every call and piece of correspondence.
How can I verify if a medical provider is in-network before my appointment?
Check your health insurance plan’s provider directory online or call the member services number on your insurance card. Ask specifically whether the provider and the facility are both in-network. For scheduled procedures, request a cost estimate and a good faith estimate in writing. If you are using TRICARE, confirm the provider accepts your specific TRICARE plan. Document the name of the representative you spoke with and the date of your call in case of a billing dispute later.