Last Updated: October 23, 2026
Quick Summary
An explanation of benefits is a statement from your health plan showing what a provider billed, what your plan allowed, what it paid, and what you may owe. It is not a bill, so compare it against the provider’s bill before paying anything.
- Check the member name and ID against your insurance card first.
- The gap between billed and allowed amount is the plan discount you do not owe.
- Compare date of service, billed amount, allowed amount, and patient responsibility on both documents.
- Do not pay a denied charge before you understand the reason code.
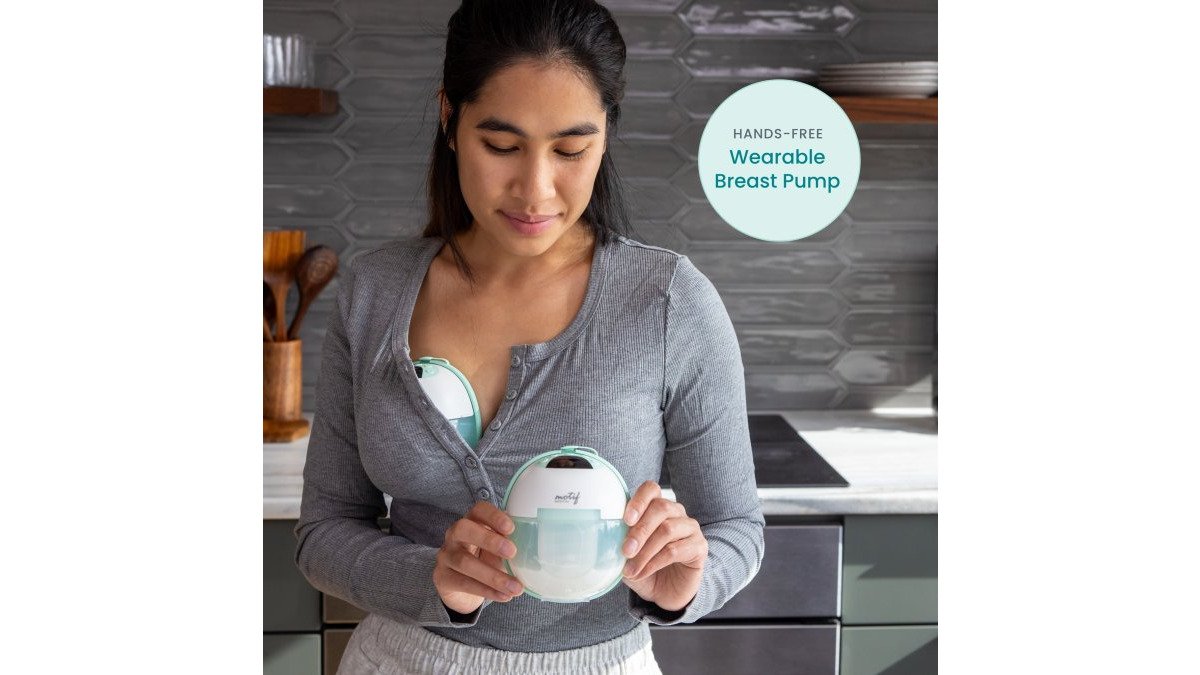
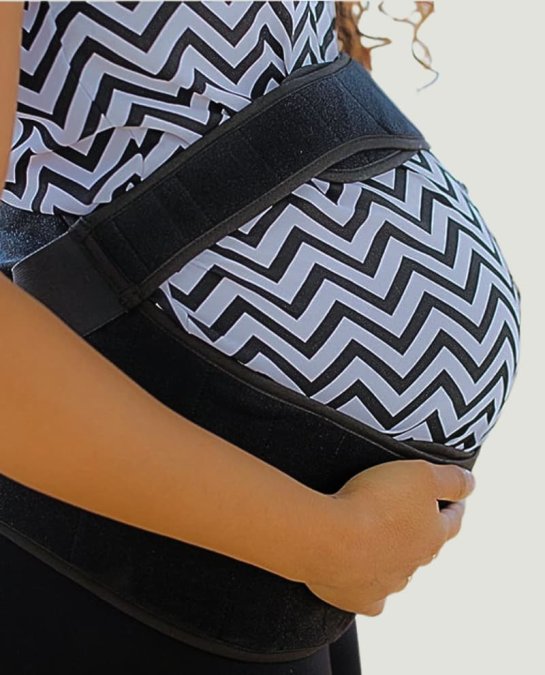
- For TRICARE, we get all authorization and ship your breast pump and maternity back support free.
Table of Contents
- What Is an Explanation of Benefits and Why It Matters
- Explanation of Benefits vs Medical Bill: What’s the Difference
- Step-by-Step: How to Read Your EOB Line by Line
- How to Understand Insurance Claim Denial Codes
- How to Dispute an Incorrect Medical Bill or EOB
- TRICARE Breast Pump Coverage and Maternity Support: What to Expect
- Conclusion
- Frequently Asked Questions
What Is an Explanation of Benefits and Why It Matters
An explanation of benefits is a statement from your health plan that shows what a healthcare provider billed, what your plan allowed, what it paid, and what you may owe.
Most people open the envelope, see a number, and panic. That number is often not what you owe.
The EOB exists to show you how your health plan processed a medical claim. It lists the date of service, the procedure, the billed amount, and your patient responsibility.
Key Sections of an EOB
A standard EOB groups information into a few blocks:
- Patient and provider information: who received care and who delivered it
- Claim summary: the claim number, date of service, and claim status
- Service description: the procedure or service, often with a billing code
Explanation of Benefits vs Medical Bill: What’s the Difference
An EOB is a summary of how your plan handled a claim. A medical bill is the provider’s request for payment.
The EOB comes from your health insurance company. The bill comes from the doctor, hospital, or supplier.
Here’s what most guides miss: the EOB is your audit trail. If the bill and the EOB disagree, the EOB usually tells you why.
How to Check Whether Your EOB Matches Your Medical Bill
Run through this checklist before you pay anything:
- Do the date of service and provider name match on both?
- Does the billed amount on the bill match the billed amount on the EOB?
- Does the patient responsibility on the EOB match the balance on the bill?
If any answer is no, call the provider’s billing office first. Then call your insurer if the mismatch remains.
Step-by-Step: How to Read Your EOB Line by Line
Start at the top and work down. Each line answers one question about your medical claim. Read the blocks in this order, because each one depends on the one above it.
- Confirm your identity and the patient. Check the member name and member ID against your insurance card. If a dependent is on the claim, confirm the dependent’s name is the one listed under patient.
- Note the date of service. This is when care happened, not when the claim was filed. A claim can appear weeks after the visit, so match the date to your calendar or appointment record.
- Read the service description. Match each procedure to what you actually received. Vague descriptions like “office visit” or “supplies” are common; if a line does not match your memory of the visit, flag it.
- Compare the billed amount to the allowed amount. The billed amount is what the provider charged. The allowed amount is the negotiated rate your plan accepts for that service. The gap between them is the plan discount, and you do not owe it.
- Check the amount paid by plan. This is what your insurance actually paid the provider. It is not the same as the allowed amount; the difference is your share.
- Review your patient responsibility. This is the total you may owe, and it is usually broken into deductible, copayment, and coinsurance. Read each component separately so you can see which one drove the number.
- Read any reason code or remark code. These explain adjustments, denials, or why a service was not covered. A code like “CO-45” typically signals a contractual adjustment, while a denial code points to a coverage decision.
- Check the claim status and appeal language. The EOB should state whether the claim was paid, denied, or pended, and it should tell you how long you have to appeal.
A Worked Example: From Billed Charge to Patient Responsibility
Definitions only go so far. Here is how one claim moves through the EOB, using a common pattern for a covered service.
- Billed amount: the provider charges $300 for the service.
- Allowed amount: your plan’s negotiated rate is $180. The $120 difference is the plan discount, and you do not owe it.
- Plan payment: your plan pays $144, which is 80% of the allowed amount.
- Patient responsibility: you owe $36, which is the remaining 20% coinsurance.
That final $36 is the number that should appear on the provider’s bill. If the bill asks for $300, the provider is billing the pre-negotiated charge, and you should question it.
The same logic applies when a deductible is involved. Suppose you have a $500 deductible and none of it has been met.
How to Tell Whether the EOB and the Bill Agree
Before you pay, put the EOB and the provider bill side by side and compare four figures: the date of service, the billed amount, the allowed amount, and the patient responsibility. If all four match, the claim is consistent. If any one differs, the mismatch tells you who to call. A billed amount that differs points to the provider’s billing office. An allowed amount or plan payment that differs points to your insurer.
Keep the EOB with the bill until the balance is resolved. If a collection notice arrives later, the EOB is your proof of what the plan actually processed.
How to Understand Insurance Claim Denial Codes
A denied claim is not always final. The EOB will show a reason code or remark code next to the denied service.
Common reasons include a missing referral, a service the plan treats as noncovered, or a procedure code that does not match the diagnosis.
Check Your Insurance Coverage →
Then decide your next move. Sometimes the provider needs to resubmit the claim with corrected details. Sometimes you need to file an appeal.
Do not pay a denied charge before you understand the code. Paying it can close the door on an appeal and leave you stuck with a bill your plan might have covered.
How to Dispute an Incorrect Medical Bill or EOB
Disputing an incorrect medical bill starts with knowing which kind of problem you have. A billing error and an insurance decision follow different paths, and mixing them up wastes time. Use the decision tree below before you call anyone.
Step 1: Decide What Kind of Problem You Have
- The provider billed the wrong amount or the wrong service. This is a billing error. The provider’s billing office fixes it by correcting the claim.
- The plan paid the wrong amount or applied cost sharing incorrectly. This is a claims processing issue. Your insurer fixes it by reprocessing the claim.
- The plan denied a service you believe is covered. This is a coverage decision. It requires a formal appeal, not a billing correction.
- The EOB and the bill do not match. This is a reconciliation problem. Compare the four key figures (date of service, billed amount, allowed amount, patient responsibility) to see which party needs to act.
Step 2: Gather Your Documents
Before you call, collect the EOB, the provider bill, and an itemized statement from the provider. An itemized statement lists each service and charge separately, while a summary bill may show only a total. Ask the provider’s billing office for the itemized version if you only have a summary. Also pull your plan’s summary plan description, which states your appeal deadline and the address or portal for filing.
Step 3: Contact the Right Party First
If the problem is a billing error, call the provider’s billing office and ask them to correct the claim. Give them the claim number from the EOB and the specific line that is wrong. If the problem is a claims processing issue or a denial, call member services at your insurer and ask them to review the claim. Ask for the representative’s name and a reference number for the call.
Step 4: File a Formal Appeal If the Denial Stands
A formal appeal is a written request that your plan reconsider its decision. Most plans set a deadline, often measured from the date on the EOB, so check your plan documents rather than guessing. Your appeal should include the member ID, the claim number, the date of service, the service in question, and a short explanation of why you believe the decision is wrong.
Step 5: Keep a Paper Trail
Log every call with the date, the representative’s name, the reference number, and what you were told. Send written correspondence by a method that gives you proof of delivery.
For guidance on your rights during an appeal, see the official consumer information on health insurance appeals. Your plan documents also spell out the appeal deadline and the levels of review available.
Ask for the name and reference number of every person you speak with. When a billing error gets fixed, that note is what moves it forward.
TRICARE Breast Pump Coverage and Maternity Support: What to Expect
TRICARE covers breast pumps for new mothers, and the process is simpler than most people expect. You do not have to decode an EOB alone, and you do not have to chase authorizations yourself.
At General Home Medical Supply, we handle the whole path for you.
We coordinate with your provider, confirm your TRICARE coverage, and manage the billing details. You focus on recovery and your baby.
The EOB is a record, not a bill.
If you have TRICARE and need a hands-free breast pump, start by checking your coverage. We will confirm what your plan allows and take it from there.
Conclusion
Reading your explanation of benefits gets easier the moment you know what each line means. Compare it to the bill, question anything that does not match, and keep your records.
If you have TRICARE and need a hands-free breast pump or maternity back support, let us handle the authorization.
Get started with General Home Medical Supply and check your insurance coverage today.
Frequently Asked Questions
Is an explanation of benefits the same as a medical bill?
No. An explanation of benefits (EOB) is a summary from your health plan showing what was billed, what the plan paid, and what you may owe. It is not a bill. A medical bill comes from your healthcare provider and is a request for payment. If you receive an EOB but no bill, you likely do not owe anything yet. Always compare the EOB to the provider’s bill to confirm the amount you owe matches the patient responsibility listed on the EOB.
How long should I keep my explanation of benefits?
Keep your EOBs for at least one year, or until you have confirmed that the claim is fully processed and any bills are paid. If you have ongoing treatments or are disputing a charge, keep them longer. Many insurers offer digital EOBs in your online account, so you can access them later. Storing them digitally reduces clutter and makes it easier to compare claims over time.
What should I do if my EOB has an error?
First, contact your healthcare provider’s billing office to verify the date of service, procedure codes, and billed amount. Then call your insurer to confirm the claim details. If the error is on the EOB, ask your insurer to reprocess the claim. If the provider billed incorrectly, ask them to submit a corrected claim. Keep notes of who you spoke with and when. For TRICARE, you can also contact the TRICARE contractor for assistance.
How can I check the status of a TRICARE breast pump claim?
Log in to your TRICARE online account or contact your regional TRICARE contractor. You will need the date of service, the provider’s name, and the claim number if available. If you ordered through a supplier like General Home Medical Supply, we handle the authorization and can help you track the claim. TRICARE covers breast pumps for new mothers, and we ship the pump and maternity back support to your home at no charge, with free shipping.
