Table of Contents
- Understanding Out-of-Pocket Medical Costs
- TRICARE Breast Pump Coverage: What You Need to Know
- How to Get Maternity Back Support Through Insurance
- Understanding TRICARE Medical Equipment Authorization
- 5 Steps to Avoid Out-of-Pocket Medical Costs
- The Self-Pay vs. Insurance Math: When Paying Cash Saves Money
- Post-Service Negotiation: How to Lower Bills After Treatment
- Conclusion: Take Control of Your Medical Costs
- Frequently Asked Questions
Last Updated: October 9, 2026
Understanding Out-of-Pocket Medical Costs
Learning how to avoid out of pocket medical costs starts with knowing what you are charged for: deductibles, copayments, coinsurance, and out-of-network care.
At General Home Medical Supply, we work with TRICARE families daily. Below: how your plan works, how TRICARE covers a hands-free breast pump and maternity back support, and five steps that keep the bill at zero.
Deductibles, Copayments, and Coinsurance Explained
A deductible is what you pay for covered care before your plan pays its share. A copayment is a flat fee at the time of service. Coinsurance is the percentage of the bill you pay after the deductible, if your plan pays 80%, you pay 20%.
The Out-of-Pocket Maximum: Your Financial Safety Net
The out-of-pocket maximum is the most you will pay for covered, in-network care in a plan year. Once you hit it, your plan pays 100% of covered services for the rest of the year. It caps your worst-case year: if you are planning a hospital birth, surgery, or ongoing care, that number tells you the most you can lose.
TRICARE Breast Pump Coverage: What You Need to Know
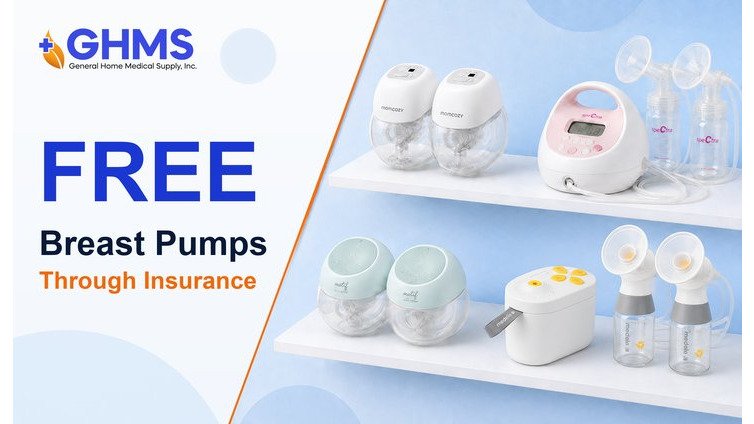
TRICARE covers a breast pump for new mothers, and for many families it arrives at no cost.
Here is what most people miss: the pump is covered, but not automatic.
Timing rules apply. Many plans let you order before your due date, but the window varies.
How to Get Maternity Back Support Through Insurance
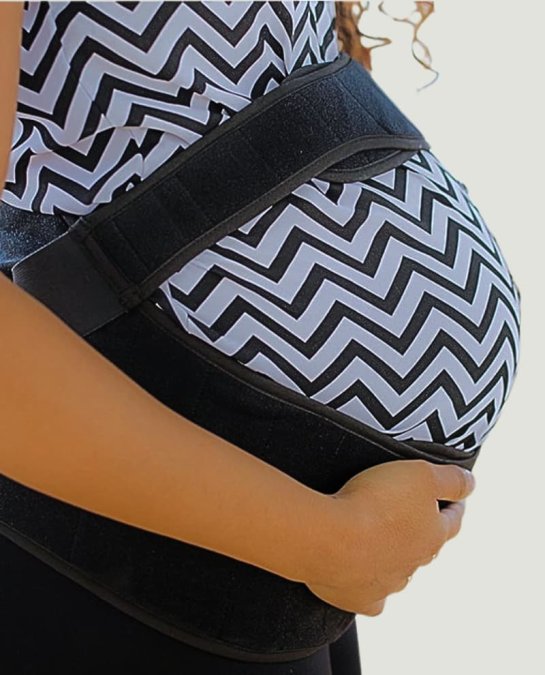
Maternity back support is often covered as durable medical equipment when prescribed.
The path to coverage looks like this:
- Get a written prescription from your OB or midwife
- Confirm the brace is a covered item under your plan
- Use an in-network supplier
The prescription is the key. Without it, a back brace is a retail purchase; with it, the same brace can be a covered medical item.
Many TRICARE families pair the back support with a postpartum abdominal binder, which supports the core after delivery and is frequently covered under the same benefit.
Understanding TRICARE Medical Equipment Authorization
Authorization is the approval your insurance gives before it pays for equipment. For TRICARE, the plan reviews the prescription, the item, and the supplier before anything ships.
Three things have to line up:
- Medical need. Your provider documents why you need the item.
- Covered item. The equipment must be on your plan’s covered list.
- Approved supplier. The company billing TRICARE must be authorized to do so.
When all three line up, the claim processes cleanly. When one is missing, you get a denial, delay, or bill.
Ask your supplier one question before you order: “Are you authorized to bill TRICARE for this item?” If the answer is anything other than a clear yes, keep looking. A supplier that cannot bill your plan correctly is the most common reason a covered item turns into an out-of-pocket charge.
This is where a supplier that handles authorization earns its keep. At General Home Medical Supply, we obtain all the authorization from your insurance, coordinate with your provider’s office, and ship the breast pump and maternity back support to your home at no charge. Shipping is free.
5 Steps to Avoid Out-of-Pocket Medical Costs
These five steps work for any plan, not just TRICARE. Run them in order to close the gaps where surprise bills hide.
Step 1: Verify Your Benefits Before You Buy
Call your plan or check your online account before buying anything. Confirm four things: Is the item covered? Is prior authorization required? Is the supplier in-network? What is left on your deductible? Ten minutes on the phone beats a denied claim six weeks later.
Step 2: Get a Prescription and Prior Authorization
Ask your provider for a written prescription naming the item and the medical reason, then confirm your plan approved it before the supplier ships.
No prescription, no coverage. That rule is close to universal.
Step 3: Use In-Network Providers and Suppliers
In-network means the provider and your plan agreed on rates. Out-of-network care can cost far more and may not count toward your out-of-pocket maximum.
For equipment, use a supplier authorized to bill your plan. For care, ask for an in-network referral before booking.
Step 4: Review Your Bills for Coding Errors
Medical billing errors are common and usually work against you. Request an itemized bill, not the summary, then check: Is every item something you actually received? Does the date of service match? Is the billing code correct? If something looks wrong, call the billing department and ask them to correct it.
Step 5: Negotiate Payment Plans or Financial Assistance
If a bill is correct but you cannot pay it, ask for help. Most hospitals have financial assistance programs and interest-free payment plans. Ask for the policy in writing and apply before the bill goes to collections.
| Step | What to Do | Who to Contact | Why It Matters |
|---|---|---|---|
| 1 | Verify benefits | Your insurance plan | Confirms coverage before you buy |
| 2 | Get prescription and authorization | Provider and plan | Unlocks the covered benefit |
| 3 | Stay in-network | Provider and supplier | Keeps costs inside your cap |
| 4 | Review the itemized bill | Billing department | Catches costly coding errors |
| 5 | Ask for a payment plan | Hospital financial office | Prevents collections |
The Self-Pay vs. Insurance Math: When Paying Cash Saves Money
Most articles say “shop around” and “ask about self-pay discounts” without showing the math. Below is the framework, plus a worked example you can copy.
The Four Numbers You Need Before You Decide
Before choosing cash or insurance, collect these four numbers.
- The cash (self-pay) price. What the provider charges a patient paying without insurance.
- The plan’s allowed amount. The negotiated rate your insurer has with that in-network provider, not the billed charge.
- Your remaining deductible. How much you still owe before your plan starts paying its share.
- Your remaining out-of-pocket maximum. How far you are from the cap that ends your cost-sharing for the year.
Ask the provider’s billing office for #1 and #2, and your plan for #3 and #4.
The Decision Framework
Run the bill through these gates in order, stopping at the first that applies.
- Gate 1, Have you already met your out-of-pocket maximum? Use insurance. Covered, in-network care is paid at 100% for the rest of the plan year.
- Gate 2, Have you met your deductible, and is the bill large? Use insurance. Coinsurance applies, but the plan is now sharing the cost, and the claim counts toward your out-of-pocket maximum.
- Gate 3, Have you NOT met your deductible, and the bill is small? Compare the cash price to the plan’s allowed amount. If cash is lower and the bill would not meaningfully move you toward your deductible, cash can win.
A Worked Example
Suppose you need an outpatient procedure. If you have met your deductible and are far from your out-of-pocket maximum, insurance wins: the plan pays its share and the claim counts toward the cap. If you have not met your deductible and the bill is small, compare the cash price to the allowed amount, if cash is lower and the claim would not move you toward your deductible, cash can be cheaper.
Check Your Insurance Coverage →
The Trap Nobody Warns You About
Paying cash for a service does not count toward your deductible or your out-of-pocket maximum. If you are close to your cap, paying cash can cost you more over the full year, even when the single bill looks cheaper. Always check your year-to-date totals before you choose cash.
How to Ask for Both Numbers
Use this script when calling the provider’s billing office:
“I’m comparing my options before I schedule. Can you give me the self-pay price for this procedure, and can you also tell me the allowed amount my insurance has negotiated with you? I want to see both before I decide.”
Then call your plan and ask:
“Can you tell me my remaining deductible and my remaining out-of-pocket maximum for this plan year?”
With those four numbers, the decision is arithmetic, not guesswork.
Where This Framework Does Not Apply
For durable medical equipment, like a breast pump or maternity back support, the math is different. These items are often covered at little or no cost when prescribed and authorized, so cash rarely wins. Confirm coverage and authorization before anything ships rather than price-shopping.
Post-Service Negotiation: How to Lower Bills After Treatment
A bill is not final until you pay it. After treatment you still have leverage. Below are the scripts, the order to run them in, and the escalation path when a billing department says no.
Step 1: Get the Itemized Bill, Not the Summary
Call the billing department and ask for a line-by-line itemized statement. The summary shows a total; the itemized bill shows every charge, code, and date.
“Please send me a fully itemized bill with the CPT and HCPCS codes for every line item, plus the date of service for each.”
Step 2: Audit the Bill Against Your Records
Compare the itemized bill to your notes, discharge paperwork, and explanation of benefits. Look for duplicate charges for the same service on the same day, services you never received, dates that do not match your records, codes that describe a more expensive service than what you got, and charges for items that should have been bundled into a single code.
Step 3: Ask for the Self-Pay Rate
If you are paying out of pocket anyway, ask the cash price. Providers often have a lower self-pay rate because they skip the claims process.
“I’m paying this myself. What is your self-pay rate for this service, and can you apply it to my account?”
Step 4: Request a Payment Plan
Most billing departments would rather set up an interest-free plan than send the account to collections.
“I can’t pay this in full today. What interest-free payment plan options do you have, and what’s the longest term available?”
Get the terms in writing before you make the first payment.
Step 5: Apply for Charity Care (Financial Assistance)
This is the step most articles skip.
“Please send me your written financial assistance policy and the application. I’d like to apply before this goes any further.”
Apply before the bill goes to collections. Approval can reduce or eliminate the balance, and the application often pauses collection activity.
Step 6: Escalate if You Are Denied
If the billing department says no, work up the ladder: ask for the billing supervisor, then the hospital’s patient advocate or ombudsman, then your state insurance department or the plan’s member services for a formal appeal. For a medical billing advocate, hire one who works on a share of what they save you.
The Script That Opens the Door
Use this when you first call about a bill you cannot pay:
“I want to resolve this bill, but the amount is more than I can pay. Before we talk about collections, can you tell me what financial assistance options you have, what the self-pay rate would be, and what payment plans are available?”
That one question puts three options on the table and signals you will work with them, not disappear.
Get the itemized bill, audit it, then ask for the self-pay rate, a payment plan, and charity care, in that order. Most people stop after the first call. The ones who escalate are the ones who get the balance reduced.
Conclusion: Take Control of Your Medical Costs
Surprise medical bills rarely come from nowhere. They come from a missing prescription, an out-of-network supplier, or an unchecked code, each preventable.
If you have TRICARE and need a hands-free breast pump or maternity back support, let us take the paperwork off your plate.
Frequently Asked Questions
Is there any way to get out of paying medical bills?
You can reduce or eliminate out-of-pocket medical costs by using in-network providers, getting prior authorization for services, and reviewing bills for coding errors. For necessary equipment like breast pumps or maternity back support, working with a supplier that handles insurance authorization can mean $0 out-of-pocket. If bills remain, negotiate a payment plan or apply for financial assistance or charity care through the hospital.
How does TRICARE cover breast pumps and maternity support?
TRICARE covers breast pumps and maternity back support when they are prescribed by a TRICARE-authorized provider and obtained from a TRICARE-approved supplier. Coverage includes hands-free breast pumps and necessary supplies. You will need a prescription and prior authorization. Working with a supplier that manages the authorization process can simplify this and ensure you receive the equipment at no cost to you, with free shipping to your home.
Can I get medical equipment shipped to my home at no cost?
Yes. If you have TRICARE or another insurance plan that covers the equipment, you can often have it shipped directly to your home at no charge. The supplier handles prescription coordination, insurance authorization, and billing, so you do not pay out-of-pocket. Shipping is free. This is common for breast pumps, maternity back support, and other prescribed medical equipment.
What is the difference between a deductible and out-of-pocket maximum?
A deductible is the amount you pay for covered services before your insurance starts paying. An out-of-pocket maximum is the most you will pay in a year for covered services. Once you reach the out-of-pocket maximum, your insurance covers 100% of covered services for the rest of the year. Knowing both helps you plan and avoid unexpected costs.